Quick Summary
A San Antonio foreclosure auction is quieter and more procedural than most people picture — a substitute trustee reads a brief legal description aloud outside the courthouse, opens bidding at a set amount, and the property sells to whoever bids highest within a matter of minutes. There’s no requirement for the homeowner to attend, and for most, there’s little practical reason to.
In This Article
- The Short Answer: What It Actually Looks Like
- Where and When This Happens in Bexar County
- Who You’ll Actually See There
- The Walkthrough: From Arrival to Your Property Being Called
- What the Trustee Actually Says and Does
- How the Bidding Itself Sounds and Moves
- What Happens the Moment It Sells
- Should You Attend Your Own Auction?
- Does Anything Change If You’re Not There?
- If You Do Decide to Attend: What to Know Beforehand
- A Quick Example: One Property’s Turn, Start to Finish
- Misconceptions About What Happens There
- Frequently Asked Questions
Most people picture a foreclosure auction as something dramatic — a packed courtroom, a booming auctioneer, families watching from the back. The reality is much smaller and quieter than that. If you’re facing a sale date and wondering what actually happens on the day, here’s a real walkthrough of the event itself.
The Short Answer: What It Actually Looks Like
A foreclosure auction in Texas is typically a brief, procedural event — a handful of people standing outside a courthouse, a substitute trustee reading a short legal description, and bidding that opens and closes within a few minutes per property. It’s nothing like a movie auction scene: no gavel banging, no dramatic bidding war in most cases, and often no crowd at all beyond a few regular investors.
Where and When This Happens in Bexar County
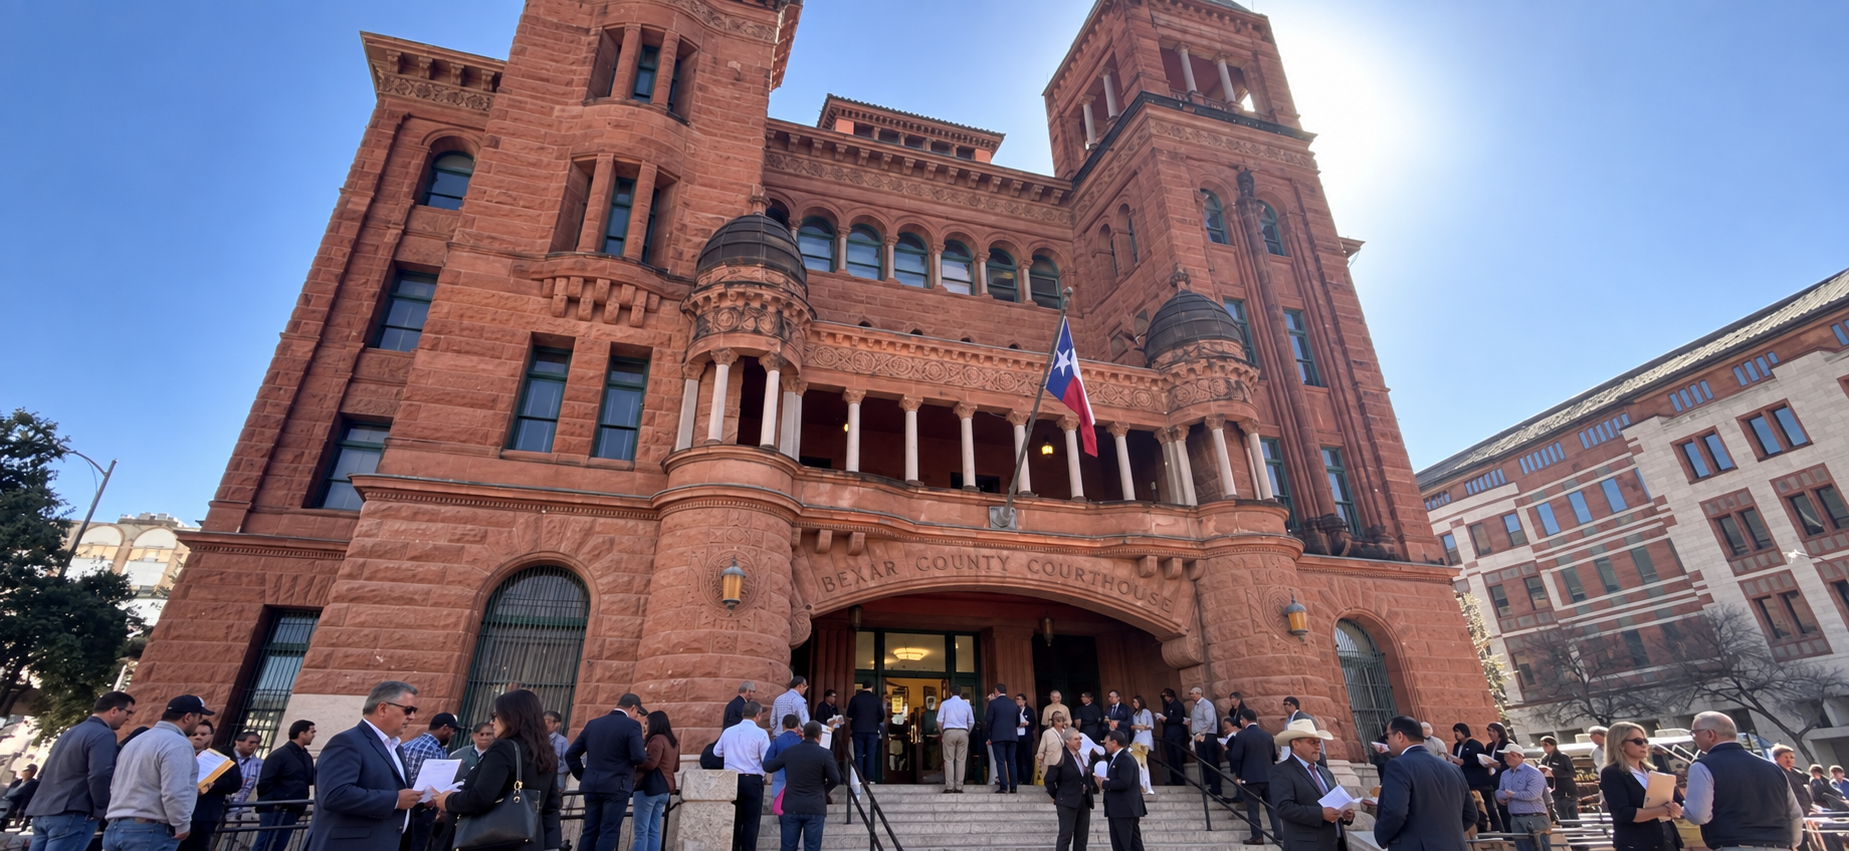
Texas law requires foreclosure sales to happen on the first Tuesday of the month, between 10 a.m. and 4 p.m., at a location designated by the county commissioners’ court — in Bexar County, this has historically been at or near the Bexar County Courthouse in downtown San Antonio. Multiple properties are typically auctioned during the same window, one after another, which is why notices list a time range rather than an exact minute for any single property.
For the legal mechanics behind this — who conducts the sale, how the opening bid is calculated, and what Texas law says about post-sale rights — see our companion guide on how Bexar County foreclosure auctions actually work. This article focuses specifically on what the event itself looks and feels like.
Who You’ll Actually See There
The people present are usually a small, familiar group rather than a large public crowd: the substitute trustee (or a representative reading on their behalf), a handful of regular real estate investors who track auction schedules closely, and occasionally a representative from the lender’s side. Homeowners themselves are rarely present — there’s no legal requirement to attend, and most people facing foreclosure choose not to.
It’s not unusual for the entire group present for a given property’s sale to be under a dozen people, sometimes far fewer, especially for properties that don’t generate much investor interest.
The Walkthrough: From Arrival to Your Property Being Called
If you were to attend, here’s roughly how the morning unfolds. Properties scheduled for that month’s sale are typically called in a sequence, often based on the order they were posted or a list the trustee is working from. Attendees mill around the designated area, checking notices and waiting for their property of interest to be called.
When it’s a given property’s turn, the trustee (or their representative) steps forward, often holding a printed copy of the Notice of Sale, and begins the brief formal process described in the next section. There’s typically no announcement system or loudspeaker — this is usually just a person speaking at a normal volume to whoever’s gathered close enough to hear.
What the Trustee Actually Says and Does
The trustee’s script is short and procedural: they identify the property (often by its legal description rather than the street address alone), confirm the terms of the sale, and announce the opening bid — typically the amount owed to the lender, sometimes called the credit bid. This whole opening statement often takes well under a minute.
There’s no dramatic buildup, no reading of the homeowner’s story, and no opportunity at this stage for the homeowner (if present) to address the trustee or the gathered bidders about the sale itself. The process is deliberately procedural, not a forum for negotiation.
How the Bidding Itself Sounds and Moves
Once the opening bid is announced, anyone present can call out a higher amount, and the trustee acknowledges and tracks the increasing bids verbally. For many properties — particularly ones without strong investor interest — nobody bids above the opening amount at all, and the sale goes to the lender’s credit bid essentially uncontested.
For properties that do attract interest, the bidding typically moves quickly between a small number of regular investors who know the local market and can move fast — this isn’t a slow, drawn-out negotiation, more a rapid back-and-forth that resolves in well under a minute once it starts.
What Happens the Moment It Sells
Once bidding stops and the highest bid is confirmed, the trustee declares the sale complete for that property, and moves on to the next one on the list. The winning bidder is generally expected to provide payment — typically a cashier’s check — the same day to finalize the transaction, after which a trustee’s deed is executed transferring ownership.
There’s no cooling-off period and no opportunity to reconsider once the sale is declared — the finality is part of why every option to stop or postpone a sale needs to happen before this moment, not during or after it.
Should You Attend Your Own Auction?
There’s no legal requirement to attend, and for most homeowners, there’s genuinely little practical benefit in doing so — you can’t stop the sale, negotiate at the event, or change the outcome by being present. Some people choose to attend anyway for a sense of closure or to see the process firsthand; others find it more emotionally difficult than helpful and prefer not to be there.
If you do attend, know in advance what to expect based on everything above: a brief, procedural, unemotional event, not a dramatic one — which can itself be either reassuring or unsettling, depending on what you were picturing beforehand.
Does Anything Change If You’re Not There?
No — the sale proceeds identically whether or not the homeowner is present. The trustee reads the same notice, the same bidding process happens, and the outcome is the same. Your presence or absence has no bearing on the legal outcome of the sale itself.
If you’re weighing whether to go, it’s worth making that decision based on your own emotional preference rather than any belief that attending changes what happens — it doesn’t.
If You Do Decide to Attend: What to Know Beforehand
If you choose to go, a few practical points make the experience easier to navigate: arrive with time to spare, since properties are sold in sequence and you won’t know exactly when yours will be called within the posted window; bring a valid photo ID, since it may be requested if you intend to participate in any way; and dress and plan as you would for any brief outdoor public gathering, since the location is typically outside on courthouse grounds rather than in an air-conditioned building.
It’s also worth knowing that trustees and their representatives conducting these sales are focused on moving through their list efficiently — they’re not equipped or expected to answer detailed personal questions about your specific loan or offer guidance about your options. Any questions about your own situation are better directed to your servicer, an attorney, or a housing counselor beforehand, not to the trustee at the auction itself.
Finally, consider bringing someone with you for support if you do decide to attend your own property’s sale — even though the event itself is brief and procedural, watching it happen can be a genuinely difficult moment regardless of how unremarkable the process looks from the outside.
A Quick Example: One Property’s Turn, Start to Finish
To make this concrete: say a property is third on that Tuesday’s list. Around 10:20 a.m., the trustee finishes the second property’s sale and moves to the third. They read the legal description, confirm the opening bid of $175,000 (the lender’s payoff amount), and ask for bids. One regular investor in attendance bids $180,000; a second investor counters at $185,000; the first investor doesn’t raise further. The trustee confirms the sale to the second investor at $185,000, they arrange payment with the trustee, and by 10:23 a.m. — roughly three minutes after it started — the trustee has already moved on to announce the fourth property on the list.
That’s a realistic sense of the pace: brief, procedural, and often over before someone unfamiliar with the process would expect it to have even started.
Misconceptions About What Happens There
A few common beliefs about foreclosure auctions don’t match reality:
- “It’s a big public event with lots of people.” Usually the opposite — a small, often quiet gathering of regular investors and trustees, not a large public crowd.
- “I can speak up and explain my situation to stop it.” There’s no mechanism for the homeowner to address the trustee or bidders to influence the sale at the event itself — everything that could change the outcome needs to happen beforehand.
- “It takes a long time, like a courtroom hearing.” Most individual property sales take just a few minutes from opening statement to completion.
- “There’s a dramatic auctioneer calling out numbers rapidly.” It’s typically a normal conversational pace between the trustee and whoever’s bidding, not a rapid-fire chant.
Frequently Asked Questions
Do I have to be present at my own foreclosure auction?
No, there’s no legal requirement, and the sale proceeds identically whether or not you attend.
Can I say something to try to stop the sale while it’s happening?
No — there’s no mechanism for the homeowner to address the trustee or bidders to change the outcome at the event itself. Anything that could stop the sale needs to happen before the auction, not during it.
How long does the actual sale of one property take?
Often just a few minutes from the trustee’s opening statement to a confirmed sale, especially for properties without significant competing bids.
What if I want to watch but not participate?
You’re free to simply observe — there’s no requirement to bid, speak, or otherwise participate if you’re present.
Is the trustee the same person every month?
Not necessarily — the substitute trustee is named specifically in each property’s Notice of Sale, and can vary between properties and lenders even at the same monthly auction.
What happens if it starts raining or there’s bad weather?
Sales generally still proceed as scheduled unless officially postponed by the county or the trustee — check with the trustee named on your specific notice if you have concerns about a scheduled date under unusual circumstances.
Can I bid on my own house at the auction to keep it?
Technically the homeowner isn’t barred from bidding, but this would require having the full bid amount in certified funds ready that day — for most homeowners facing foreclosure, this isn’t a realistic option, which is exactly why the options covered in our other guides need to happen beforehand.
Does the sale happen exactly at the time listed on my notice?
Not necessarily to the minute — notices typically list a time window (10 a.m. to 4 p.m.) rather than an exact time, since multiple properties are sold in sequence during that window.
Will I be notified afterward if my house sold?
You’re not automatically notified by the trustee, though the sale is a matter of public record, and any next steps (such as an eventual eviction process if you’re still occupying the home) would come through separate formal notice.
Can family members or friends attend on my behalf?
Yes — there’s no restriction on who can be present to observe a sale, and having someone attend in your place is a reasonable option if you’d rather not be there yourself but still want to know what happened.
Is there a way to watch or confirm the sale result without physically attending?
The completed sale becomes part of the public record shortly afterward, and your loan servicer or the trustee’s office can typically confirm the outcome if you call after the scheduled auction window has passed.
Do investors research properties before showing up to bid?
Regular auction investors typically do research properties in advance — reviewing public records, sometimes driving by the exterior — since they’re making a same-day purchase decision without the inspection period a traditional buyer would have.
Is the location always exactly the same every month?
It’s generally consistent, since the county commissioners’ court designates a standing location for these sales rather than changing it monthly, but always verify the exact designated area against your specific Notice of Sale rather than assuming from memory of a past visit.
What’s the very last moment something could still stop the sale from happening?
Legally, right up until the trustee declares a completed sale — a bankruptcy filing’s automatic stay taking effect, for instance, could halt things even minutes before a property is called, though this requires the filing to already be in motion, not started that same morning at the courthouse.
Do all properties on the list actually get sold that day?
Not always — a property can be postponed or pulled from the sale before its turn is called, for reasons ranging from a last-minute reinstatement to a bankruptcy filing, which is part of why the list a trustee works from that day isn’t necessarily final until each individual property is actually called.
How Cornerstone Property Buyers Can Help
If you’re facing an upcoming sale date and want to avoid your property ever reaching the courthouse steps, we buy houses in San Antonio and across Bexar County as-is, for cash, with closings possible in as little as 7 days — often fast enough to close before a scheduled auction. Request a no-obligation cash offer to see if that timeline works for you.
This article is for general information only and isn’t legal or financial advice. If you’re facing a scheduled foreclosure sale, consider speaking with a HUD-approved housing counselor or a Texas foreclosure attorney about your specific situation.
Get a fair cash offer in 24 hours — no repairs, no fees, no obligation.
Get My Cash Offer → Or call: 210-920-7915